Hewlett Packard Enterprise (HPE) is a company that sells servers, storage, and networking equipment to large businesses and cloud providers.
To increase its earnings, the company decided to buy Juniper Networks in early 2024, but due to various reasons, couldn’t close the deal until the next year. Then in July 2025, HPE successfully bought Juniper for $14 billion.
That decision is now starting to pay off.
At HPE’s Networking Investor Day on Sept. 30, the company roughly doubled its long-term growth outlook for the networking market and raised its fiscal 2027 outlook for the business. Morgan Stanley responded the next day by lifting its price target on the stock.
What Morgan Stanley changed in its HPE call
The Morgan Stanley analyst who made the call is Erik Woodring. Woodring has covered IT hardware at Morgan Stanley for several years, and he leads the firm’s research on names including Apple and Dell.
In a Morgan Stanley research note shared with me, Woodring raised his HPE price target to $72 from $67, and he kept his Overweight rating. He also raised his bull case estimate to $94.
Also read: Morgan Stanley revisits Micron stock price target amid stellar growth
His upgrade came about a month after HPE reported its fiscal third-quarter results. During the third quarter, the company’s revenue grew 33.68% year over year to $12.21 billion, beating Wall Street’s earnings expectations by 18.41% and revenue estimates by 1.83%.
HPE gave an early fiscal 2027 earnings estimate of $4.40 to $4.60 per share, and Woodring’s new price target suggests he believes HPE could reach or exceed that range as its networking business continues to grow.
Why networking has become HPE’s biggest growth driver
HPE now expects its networking market to grow by about 18% each year until the end of 2029, roughly double what the company told investors last year.
HPE also said it plans to grow its networking sales at that same high-teens pace. That would mean the company will start taking market share from rivals like Cisco.
“HPE’s Networking market growth outlook has effectively doubled since last year, while HPE’s relative growth positioning has strengthened,” Woodring wrote in the note.
More Tech Stocks:
- Bank of America backs HPE stock before crucial investor day
- Wall Street doubles down on Microsoft stock for investors
- 5-star analyst sets jaw-dropping price target on SanDisk stock
Inside HPE’s networking business, the company expects data center networking to grow the fastest. HPE expects data center networking to grow about 50% a year through the end of fiscal 2029.
The company also expects routing to grow about 20% a year, while sales of networking gear for office campuses and branch locations are expected to grow at high-single-digit rates.
“AI is reshaping the technology stack, making the network more strategic and driving significant new demand from enterprises and service providers,” Rami Rahim, who was the CEO of Juniper before HPE bought the business, said. Rahim now leads HPE Networking.
The AMD Helios deal and the $1.2 billion Vultr win
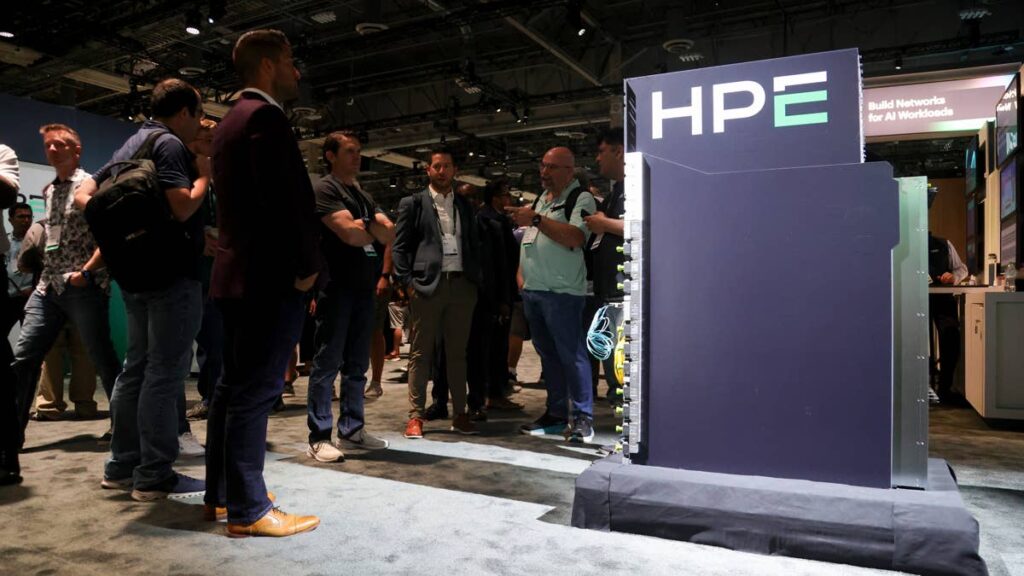
Another factor that supports HPE’s new outlook is its partnership with AMD on the Helios rack.
The Helios rack is like a ready-to-use AI computer that comes with AI servers and HPE’s networking switches built inside. HPE can sell the full thing or just the networking parts alone to companies that want to build their own.
Related: Morgan Stanley doubles down on SpaceX stock verdict for investors
HPE confirmed on Sept. 30 that it received its first Helios order. The large $1.2 billion deal came from Vultr for the full Helios cabinets. A major deal like that is a sign that Helios is already bringing in real money for HPE.
However, the company might face some supply constraints. “The FY27 Networking outlook moves higher just one month after earnings as HPE incorporates the incremental Helios opportunity, with supply, not demand, remaining the key constraint,” Woodring wrote.
If HPE can get the parts it needs to avoid supply issues, Woodring feels the company could achieve its targets.
What everyday investors should consider after HPE’s rally
HPE stock has already climbed 186.84% year to date and increased by 7.36% on Oct. 2 alone, closing at $69.33. That means the company’s shares are already close to Morgan Stanley’s new $72 base case, and it’s why I believe a lot of the good news is probably already priced in.
For Woodring’s $94 bull case to happen, HPE’s AMD Helios orders have to keep growing. The Juniper cost savings will also need to come in faster, and server demand would have to stay strong until the end of fiscal 2028.